In my experience, some of the most frustrating tax situations happen when someone makes a large purchase based on a tax benefit they heard about — and only later finds out that they did not meet one of the requirements.
The new car loan interest deduction is a good example.
I expect more clients will start asking about this deduction as they shop for vehicles in 2026. And my first response would be this: yes, the deduction can be valuable, but don’t assume your car qualifies simply because you financed it.
There are several details worth checking before you sign the loan documents.
The New Deduction Sounds Simple — But It Has Conditions
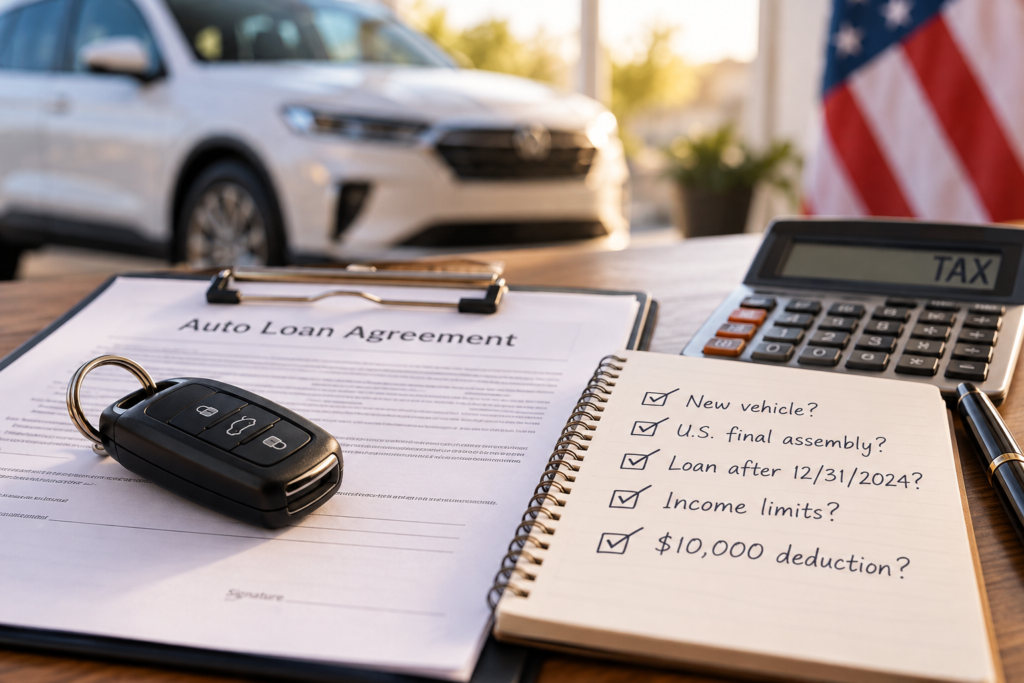
For tax years 2025 through 2028, certain taxpayers may deduct up to $10,000 per year of qualified passenger vehicle loan interest.
One thing I like about this provision is that you do not have to itemize deductions to benefit from it. A taxpayer who takes the standard deduction may still qualify.
But the $10,000 number tends to get most of the attention, while the eligibility rules get much less attention.
That is where problems can start.
For the interest to qualify, the loan generally must have been incurred after December 31, 2024, and it must have been used to purchase a qualifying vehicle secured by a first lien.
More importantly, the vehicle generally needs to be a new vehicle whose original use begins with you.
So if you purchase a used vehicle, even a relatively new one, you generally cannot assume that the interest will qualify for this particular deduction.
Before Buying the Car, I Would Check Where It Was Assembled
This is probably the rule I would want clients to know before they walk into the dealership.
The vehicle must have undergone its final assembly in the United States.
And this should not be determined simply by looking at the brand name.
A vehicle from a U.S. automaker may have been assembled outside the United States. At the same time, a vehicle sold by a foreign-headquartered manufacturer may have been assembled at a U.S. plant.
So I would not make this decision based on whether the vehicle “looks American.”
Instead, check the specific vehicle.
The IRS final regulations allow taxpayers to use information from the vehicle’s VIN or the final assembly location shown on the vehicle label, sometimes referred to as the window sticker.
That is the kind of detail I would rather verify before purchasing the car, not several months later while preparing the tax return.
The $10,000 Deduction Is Not $10,000 for Everyone
Another misunderstanding I expect to see is the assumption that every qualifying buyer automatically receives a $10,000 deduction.
That is not how it works.
First, $10,000 is the annual maximum amount of qualified interest that may be taken into account per federal tax return.
Second, the deduction begins to phase out when modified adjusted gross income exceeds certain levels.
For most filing statuses, the phaseout begins once MAGI exceeds $100,000. For married couples filing jointly, it begins once MAGI exceeds $200,000.
The deduction is reduced by $200 for each $1,000 — or portion of $1,000 — that income exceeds the applicable threshold.
This is why I would not evaluate this deduction by looking only at the car and the loan.
Your income matters too.
A vehicle can meet every eligibility requirement and still produce a much smaller tax deduction than the buyer expected because of the income phaseout.
Business Owners Should Be Even More Careful
For business owners, there is another layer to consider.
A vehicle may be used partly for business and partly for personal purposes, and the tax treatment of the related expenses can become more complicated.
The IRS final regulations address situations where vehicle loan interest may potentially qualify as passenger vehicle loan interest while some of the interest may also be connected to business use.
This is where I would avoid applying a general rule from an article or social media post.
When a business owner buys a vehicle, I normally want to look at the entire picture: how the vehicle will actually be used, how it is titled and financed, whether the taxpayer is using the standard mileage method or actual expenses, and what other deductions are available.
The goal should not be to chase one deduction.
The goal should be to determine the tax treatment that makes sense for the taxpayer’s actual situation.
Keep the Loan Documents
Taxpayers sometimes think about documentation only after receiving an IRS notice.
It is much easier to keep the right records from the beginning.
If you plan to claim this deduction, I would keep the purchase agreement, financing documents, VIN information, and documents showing the vehicle’s final assembly location.
Lenders also have new information-reporting requirements for qualifying vehicle loans. Under the new rules, lenders receiving at least $600 of interest on certain qualifying vehicle loans generally have reporting obligations.
But I would still recommend keeping your own records rather than assuming every document will automatically appear exactly when you need it.
One More Thing: Don’t Buy a Car for the Tax Deduction
This may be the most practical advice in this entire article.
A tax deduction reduces taxable income. It does not reimburse the cost of the vehicle or the interest you paid.
If you were already planning to purchase a vehicle and the loan qualifies, this deduction can certainly help.
But I would never recommend taking on unnecessary debt simply because the interest may be deductible.
The vehicle price, interest rate, loan term, insurance cost, expected use of the vehicle, and your overall cash flow still matter far more than the deduction alone.
Tax planning works best when the tax benefit supports a good financial decision — not when the tax benefit becomes the reason for making the decision.
Thinking About Buying a Vehicle?
If you are considering purchasing or financing a vehicle and want to know how the new car loan interest deduction may apply to you, it is worth reviewing the details before completing the purchase.
A short tax-planning conversation before a transaction can sometimes prevent a much more complicated conversation after the year is over.
At WiseBeing Tax & Accounting, we help individuals and business owners look beyond a single deduction and understand how financial decisions fit into their overall tax situation.
Schedule a consultation with WiseBeing Tax & Accounting to discuss your tax planning questions.